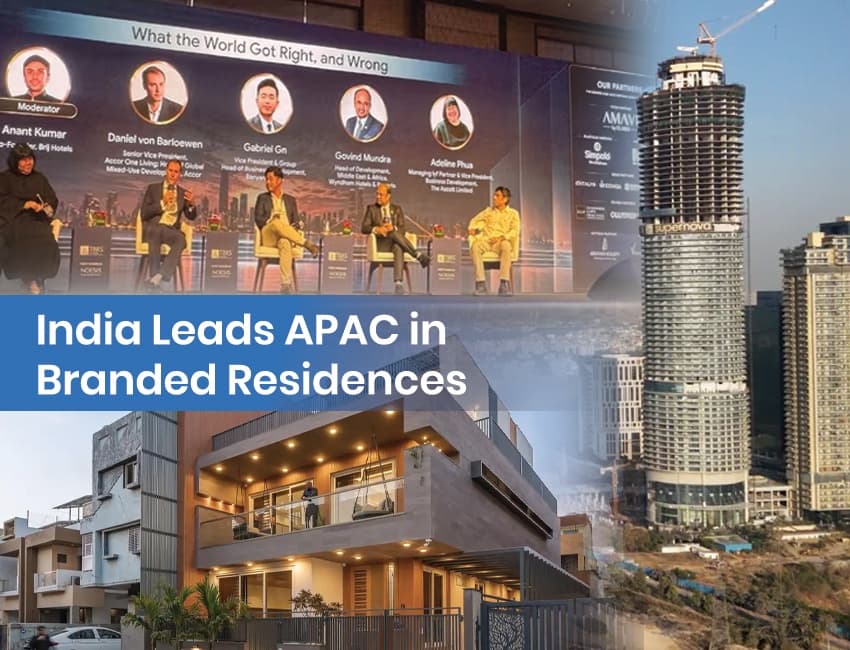
India leads the APAC region in branded residences by value at ₹92,000 crore. The sector is in a high-growth phase, and branded residence projects are expected to rise from 47 (2023) to 85 (2028).
As per NOESIS Hotel Advisors’ The Landscape of Branded Residences in India, Edition 3, Delhi-NCR has the highest number of branded residence projects. Goa and Alibaug, in addition to Indian metros, and Rishikesh are other emerging branded residences markets.
India’s Share in Asia Pacific at 21% by Value
India represents around 21% of branded residences values in Asia Pacific at around ₹4.53 billion. Vietnam represents India’s closest competition, with branded residence values at around ₹8 billion. In total supply, India ranks fourth after Australia, China, and Japan in the Asia Pacific region.
There is a growing need for residences that integrate high-quality real estate with services, facilities, and offerings of a hotel, thus creating a robust and valuable real estate brand.
Our report focuses on 47 branded residence projects in India, of which 15 are completed. The markets covered in the report are Mumbai, Bengaluru, Hyderabad, Chennai, Noida, Gurugram and Bhubaneswar, among others.
Branded Residence Projects in Delhi-NCR are the Most in India
Of the branded residence projects in India, those located in Delhi-NCR are the most. The region has 15 projects, followed by Mumbai, which has six. The presence of branded residences in Delhi-NCR points to the luxury housing market in the region, catering to the affluent buyer and investor segments.
Given the market conditions, it is evident that Gurugram, along with Noida, is heading in the same direction as Delhi, with an increase in the number of branded residences, reflecting the overall trend of development and modernisation of the region.
Branded Residence Projects to be Located Beyond Metros
It is expected that the number of branded residence projects in India will increase from 47 to 85 by 2028. The report suggests that in the next development cycle, about 45% of the projects may be located outside metropolitan markets, compared to 8% in the current cycle. Projects identified outside metropolitan markets include Goa, Alibaug, Rishikesh, Bhubaneswar, and Mohali.
The recent trend shows that branded residences will not be restricted to major cities. Developers and hotel companies will focus on recreational and secondary cities and destinations where there is a customer demand for second homes, vacation homes, and lifestyle properties.
Hyderabad Expected to Add Around 1,200 Branded Homes
Among the major cities of India, branded residences will see an upsurge in Hyderabad in the near future.
The report expects that by the year 2028, approximately 1,200 branded homes will be added to Hyderabad's real estate market through 7 development projects.
This positions Hyderabad as a key market for branded residences.
Branded Homes Command a 32% Average Premium
Branded homes, in comparison to traditional and non-branded homes, fetch a significant premium.
Per the NOESIS report, branded homes in India have an average premium of 32%, aligning with the global average. However, there is a fair degree of variance across markets. Pune, for example, commands a premium of 44%, with Kolkata at 42%. Hyderabad, which is at the lower end of the spectrum, commands approximately 25%.
It is the brand and the overall experience that helps justify the premiums commanded by branded residences.
Record Growth in Supply of Branded Residences in India
The past year has seen rapid growth for branded residences in India. The report tracks 38 projects that are operational or have been launched, totalling 10,452 units, across 10 different markets.
Supply saw more than a threefold increase in 2025, going from 1,015 units to 3,181 units. Additionally, since the beginning of 2025, projects have launched to the market a further 5,156 units.
This volume is notable as the units launched since the start of 2025 are approximately double the combined total of units launched during the previous seven years.
Strong Transaction Activity
Transaction activity has also strongly increased. The report states that the annual transaction value for branded residences showed a compound annual growth rate of 49% from 2019 to 2025. From 2018 to 2025, branded residences transactions reached a value of approximately ₹47,278 crore.
2025 is expected to be strong and maintain the level of transaction activity seen in 2025.
Non-Hospitality Brands Lead the Indian Market
The global branded residences market has hotel brands in the majority, but in India, fashion, design, and lifestyle brands dominate.
Currently, 73% of branded residential units in India are made up of non-hospitality brands, compared to about 20% globally.
However, this could rapidly shift. NOESIS expects the next 24 months to see hotel brands quickly reduce this gap, as leading International and Indian hotel groups start to operate in India's branded residences market.
It is expected that this shift will result in more projects containing hotel residential ownership and integrated hospitality, combined with professional property management services.
INCREASE IN HIGH-NET-WORTH INDIVIDUALS SPURS GROWTH
India's high-net-worth population is increasingly becoming an important customer base for high-end residential properties.
As of now, India has 19,877 ultra-high-net-worth individuals, which is a 63% increase since 2021. In the first half of 2026, homes sold for ₹1 crore or more accounted for 71% of the total sales in the top 7 cities, which was 62% during the same period last year.
Sales of "branded residences" are also surging. The report says that 68% of all branded residences have already been sold.
According to the report, the main driver of the demand for branded residences is not simply the presence of a well-known brand. Other factors that play an equally important role are location, brand positioning, the project itself, the operating partner, and price.
Future of Branded Residences in India
Several new markets for branded residences in India are expected to further boost the growth of this sector. These markets include leisure and second-home destinations as well as tier 2 and tier 3 cities.
It is projected that the number of branded residential projects in India will almost double from 47 to 85 by 2028. It is also projected that the secondary home segment in India, which includes locations like Goa and Alibaug, will strengthen in the future.
The report was launched at The Branded Residences Summit 2026 (TBRS 2.0), held in Mumbai on October 7. About 350 people, mainly developers and brand representatives, attended the event organized by Amavi by Clarks.
According to Nandivardhan Jain, founder and CEO of NOESIS Hotel Advisors and the curator of TBRS, Indian customers are ready to pay for branded residences, and the next phase of development will take branded living into other cities and leisure destinations. Jain also added that for branded residences to maintain their value, long-term project feasibility will be critical, and partners for development and operations will be essential, along with consistent service delivery.
Read More: Delhi MCD Launches Drone Survey to Map Properties and Identify Tax Discrepancies
Source: Hindustan Times